
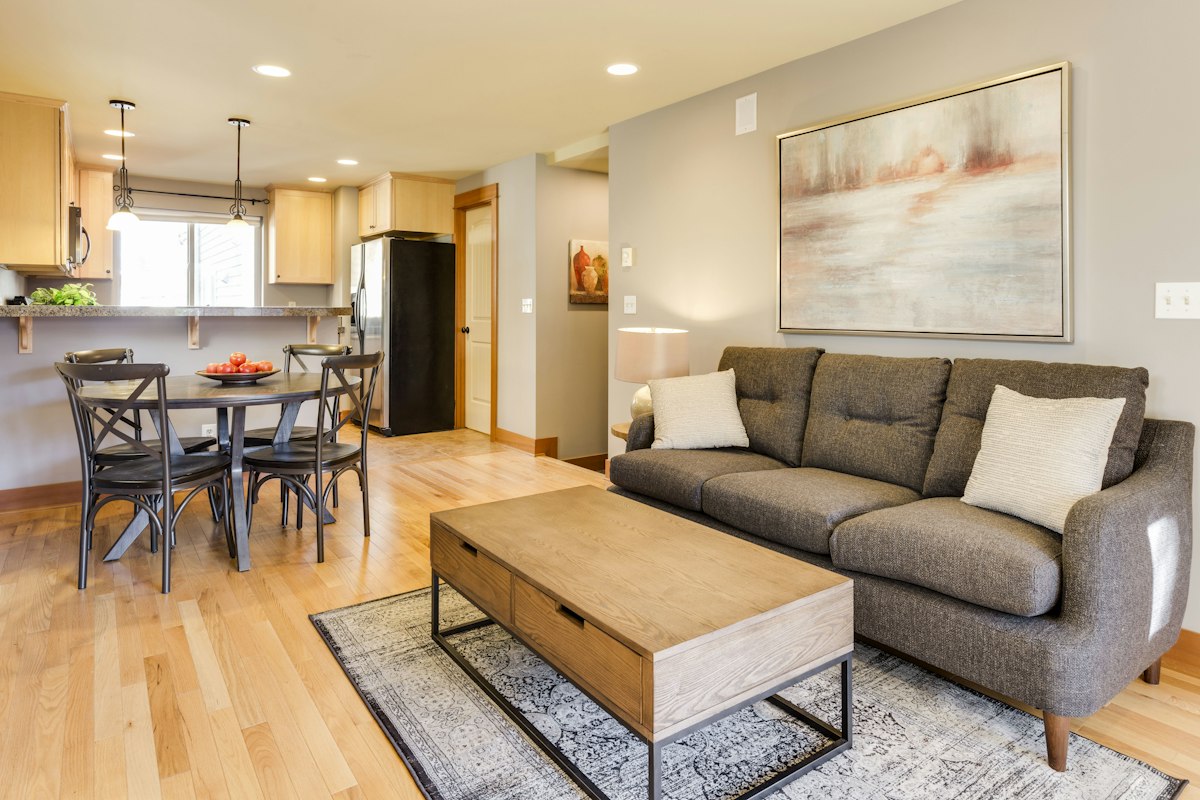
Somewhere between the subsidized world of Low-Income Housing Tax Credit (LIHTC) developments and the premium rents of Class A market-rate apartments lies one of commercial real estate's most underserved and misunderstood asset classes: workforce housing. These are the apartment communities that house teachers, nurses, first responders, retail workers, and the countless other professionals who earn too much to qualify for income-restricted housing yet too little to comfortably afford market-rate rents in most major metros. As the affordability crisis deepens across the United States, workforce housing has moved from a niche investment conversation to a mainstream capital allocation priority, and the financing landscape is evolving rapidly to keep pace.
Understanding the Workforce Housing Spectrum
Workforce housing is generally defined as rental housing affordable to households earning between 60% and 120% of the Area Median Income (AMI). Unlike affordable housing, workforce housing typically carries no long-term regulatory agreements or rent restrictions enforced by government agencies. Unlike Class A market-rate multifamily, it does not compete on luxury amenities or premium locations. Instead, it occupies a practical middle ground: naturally occurring affordable housing (NOAH) that serves the backbone of the American workforce.
According to the National Low Income Housing Coalition's 2024 Out of Reach report, a full-time worker must earn at least $32.11 per hour to afford a modest two-bedroom rental at fair market rent nationally, a figure that places millions of working households in a perpetual squeeze. Meanwhile, the Harvard Joint Center for Housing Studies reported in 2024 that cost-burdened renters, those spending more than 30% of income on housing, now number over 22 million households nationwide. These figures underscore why workforce housing is not merely an investment thesis but a genuine societal need.

The Financing Challenge and Why It's Different
Financing workforce housing presents a distinct set of challenges that set it apart from both affordable housing deals and conventional market-rate multifamily transactions. On the affordable side, LIHTC projects benefit from federal tax credits, state agency allocations, and below-market debt through programs like HUD Section 8 and HOME Investment Partnerships. On the market-rate side, lenders are comfortable underwriting stabilized Class A assets with strong rent growth projections and institutional sponsorship. Workforce housing, however, often falls into a gray zone where neither toolkit applies cleanly.
Naturally occurring affordable housing properties are frequently older vintage, Class B or C assets that require capital improvements to maintain habitability without triggering rent increases that would price out existing tenants. This creates what lenders call a "value-add tension": the improvements necessary to stabilize or reposition the asset may conflict with the affordability preservation mission. Lenders must therefore underwrite these deals with a nuanced view of both the physical asset and the tenant base's income profile.
According to CBRE's 2024 U.S. Multifamily Outlook, workforce housing assets in secondary and tertiary markets have demonstrated rent growth resilience of 3.5% to 5.2% annually, outperforming many Class A urban submarkets where new supply has compressed rents.
Despite these complexities, a growing roster of agency and non-agency loan programs has been structured specifically to address workforce housing's unique capital needs. Borrowers who understand how to navigate these options are finding that attractive leverage and competitive pricing are well within reach.
Key Loan Programs for Workforce Housing Investors
The financing options available for workforce housing span a broad range of structures, from government-sponsored enterprise programs to bridge lending and CDFI debt. Below is an overview of the most impactful programs active in the 2024-2025 market cycle:
- Fannie Mae Multifamily Affordable Housing (MAH) and MTEB Programs: Fannie Mae offers mission-driven execution for properties where at least 20% of units are affordable at or below 80% AMI. These executions provide pricing benefits, reduced fees, and flexible underwriting compared to standard DUS loans.
- Freddie Mac Targeted Affordable Housing: Similar to Fannie's MAH program, Freddie Mac's TAH executions support preservation deals and workforce housing through enhanced loan terms, including higher LTVs and lower debt service coverage ratio (DSCR) requirements in certain circumstances.
- FHA 223(f) and 221(d)(4): HUD-insured products remain among the most powerful tools for workforce housing, offering non-recourse, long-term fixed-rate financing at leverage levels up to 85-87% LTV for qualifying properties. While the processing timeline is longer, the economics are compelling for the right deal.
- CDFI and State Housing Finance Agency Debt: Community Development Financial Institutions (CDFIs) and state HFAs frequently offer subordinate debt, gap financing, or first-mortgage products specifically designed for workforce housing preservation. These sources are especially valuable for mixed-income repositioning deals.
- Bridge-to-Agency Programs: For value-add workforce housing acquisitions that are not yet agency-eligible, short-term bridge loans with a structured path to Fannie Mae or Freddie Mac permanent financing provide the flexibility to complete renovations while locking in an exit strategy from day one.
- Life Company and Debt Fund Lending: A growing number of life insurance companies and private debt funds have added workforce housing to their target allocations, attracted by the asset class's defensive cash flow characteristics and strong occupancy performance through economic cycles.

Underwriting Considerations and Market Dynamics
Underwriting a workforce housing deal requires lenders and borrowers alike to think carefully about rent achievability, tenant income stability, and the long-term preservation of affordability. Unlike luxury multifamily, where rent concessions and lease-up absorption are primary risks, workforce housing underwriting tends to focus on deferred maintenance exposure, property insurance escalation in catastrophe-prone markets, and the impact of renovation costs on in-place tenants.
In 2024 and into 2025, insurance costs have become one of the most significant underwriting variables for workforce housing in states like Florida, Texas, Louisiana, and California. According to data from the Mortgage Bankers Association, commercial property insurance premiums for older multifamily assets in high-risk states increased by an average of 18% to 35% between 2022 and 2024, compressing net operating income and creating underwriting friction that borrowers must proactively address with detailed insurance cost modeling and competitive bidding documentation.
Despite these headwinds, demand fundamentals for workforce housing remain structurally robust. Household formation among the 25-to-44 age cohort, the primary demographic for workforce rentals, continues to outpace new supply in most secondary and tertiary markets. Vacancy rates for Class B and C multifamily assets tracked by CoStar averaged just 5.8% nationally through Q3 2024, compared to 8.1% for Class A product in the same period. This occupancy premium underscores the defensive quality of workforce housing as an investment through cycles of new supply and economic uncertainty.
Investors who approach workforce housing with a disciplined capital stack, pairing the right permanent debt product with appropriately structured equity and, where applicable, soft subsidy sources, are finding that risk-adjusted returns compare favorably with nearly any other commercial real estate asset class available today. The key lies in partnering with a financing advisor who understands both the mission-driven nuances and the hard financial math of these transactions.
Looking ahead, the convergence of persistent housing undersupply, federal and state policy interest in preservation financing, and growing institutional capital targeting workforce housing suggests that this segment will remain one of commercial real estate's most active and capital-intensive arenas through the remainder of this decade. Investors, developers, and property owners who build fluency in workforce housing finance today will be exceptionally well-positioned to capture both financial returns and lasting community impact as the market continues to evolve.


